Timing the Cashout: How Serious High-Rollers Treat Withdrawals as a Financial Strategy
Among recreational players, a withdrawal is a simple transaction — winnings accumulate, and eventually the funds move to a bank account. For the high-roller operating at a genuinely elite level, however, the cashout is a financial event that demands the same deliberate planning as any significant capital movement in a managed investment portfolio. The when matters as much as the how much, and the most sophisticated members of the gaming community have developed structured frameworks to ensure their withdrawal timing works in concert with broader financial objectives.
At K8 VIP Elite, where members regularly move meaningful sums across their gaming operations, the distinction between reactive cashing out and strategic withdrawal scheduling represents one of the clearest dividing lines between amateur and professional thinking.
The Tax Calendar as a Governing Framework
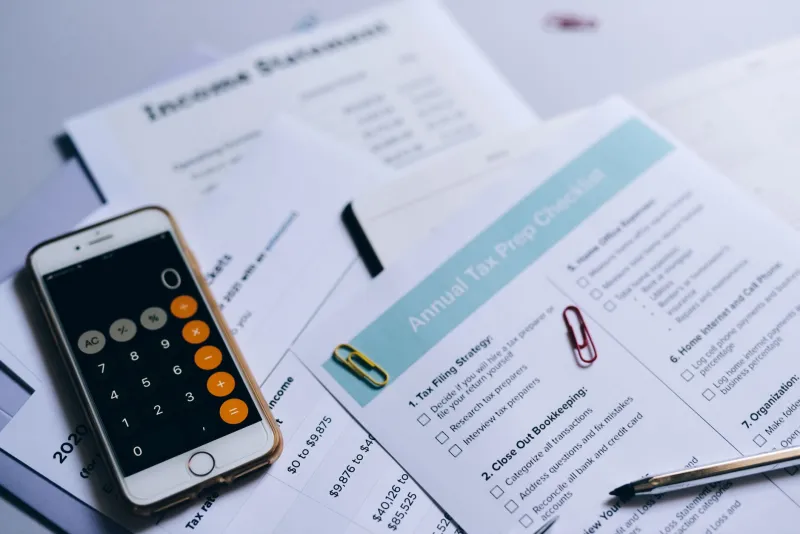
The United States federal tax code treats gambling winnings as ordinary income, which means that every substantial cashout carries immediate implications for a player's effective tax rate. For high-volume players whose winnings push them into upper marginal brackets, the timing of a withdrawal can determine whether a given sum is taxed at 32 percent or 37 percent — a difference that, on a six-figure cashout, is not trivial.
Sophisticated players approach the calendar year with a running projection of their adjusted gross income. When a strong quarter produces outsized returns, the instinct to cash out immediately must be weighed against the possibility that pulling funds in December — versus deferring to January — could shift that income into a new tax year where losses, deductions, or lower baseline income provide more favorable treatment.
This is not tax evasion. It is tax planning, and the IRS explicitly permits taxpayers to manage the timing of income recognition within legal boundaries. Elite players who work with CPAs experienced in gaming income treat the year-end period not as an arbitrary date on the calendar but as a strategic inflection point that shapes their net financial outcome for the entire year.
Threshold Awareness and Reporting Mechanics
Beyond bracket management, serious players maintain an acute awareness of the reporting thresholds that govern how gaming income is documented and transmitted to federal authorities. The $600 threshold for W-2G issuance on certain game types, and the $10,000 currency transaction reporting requirements that apply to cash movements, are not obstacles to be circumvented — they are structural features of the regulatory environment that informed players account for in their planning.
Understanding these thresholds allows elite players to structure their cashout schedules in ways that minimize administrative friction and ensure their records remain clean and defensible. A player who withdraws in a disorganized pattern — large sums followed by gaps followed by erratic smaller amounts — creates a paper trail that is difficult to reconcile at tax time and potentially invites unnecessary scrutiny. A player who withdraws according to a documented schedule, coordinated with professional counsel, maintains clarity and control over their financial narrative.
It bears emphasis that structuring withdrawals with the specific intent to evade reporting requirements is a federal offense. The goal of threshold-aware planning is operational clarity and tax efficiency — not evasion. Any player implementing a withdrawal framework should do so in explicit consultation with a licensed tax professional.
Coordinating with Accountants: The Professional's Approach
The most disciplined high-rollers do not make significant withdrawal decisions in isolation. They maintain ongoing relationships with accountants who specialize in gaming income — professionals who understand the nuances of the Schedule C versus Schedule A treatment debate, the mechanics of loss documentation, and the quarterly estimated tax obligations that accompany substantial gaming income.
These relationships function most effectively when they are proactive rather than reactive. Rather than delivering a year's worth of transaction records in April and asking an accountant to make sense of them, elite players engage in quarterly reviews that allow their advisor to model the tax implications of different withdrawal scenarios in real time. If a player is projecting a strong November, their accountant can advise on whether accelerating a cashout before year-end or deferring it into January produces a better outcome given the player's full income picture.
This kind of coordination requires organizational discipline — maintaining accurate records of deposits, withdrawals, wins, and losses across every platform in a player's portfolio. But the payoff in tax efficiency and financial clarity is substantial. Players who treat their gaming operations as a managed financial enterprise consistently outperform those who treat it as a hobby with occasional large transactions.
Multi-Month Cash-Out Planning and Operational Flexibility
For players whose gaming bankrolls represent a meaningful portion of their overall net worth, withdrawal timing also intersects with liquidity management and operational flexibility. A player who cashes out aggressively every time their balance peaks may find themselves with insufficient platform capital to capitalize on favorable conditions — a high-value tournament, a limited-time odds movement, or a promotional window that rewards active balances.
Conversely, a player who never withdraws — allowing winnings to accumulate indefinitely on a single platform — is concentrating counterparty risk in a way that sophisticated capital managers consistently warn against. The optimal approach involves a documented drawdown schedule: a plan that specifies the conditions under which funds will be moved, the amounts that will remain as operational capital, and the cadence at which profits will be transferred to external accounts.
Some elite players implement a tiered approach. A defined operational reserve — sufficient to sustain their typical monthly wagering activity without interruption — remains on platform. Amounts above that threshold are eligible for scheduled withdrawal on a monthly or quarterly basis, with the specific timing determined by tax calendar considerations and any near-term opportunities that might benefit from additional platform liquidity.
The Withdrawal as a Signal of Operational Maturity
There is a less quantifiable dimension to strategic withdrawal planning that elite players often acknowledge privately: the discipline required to execute it is itself a marker of operational maturity. The impulse to move winnings immediately — to convert digital balances into tangible funds as quickly as possible — is a psychological reflex that serves recreational players but handicaps professionals.
Elite members who have developed a structured withdrawal framework report that the discipline extends naturally into other areas of their gaming practice. The same analytical rigor that produces a well-considered cashout schedule tends to produce more thoughtful wagering decisions, more rigorous bankroll management, and a more composed response to variance.
At K8 VIP Elite, the infrastructure supporting our highest-tier members is designed to accommodate exactly this kind of professional operating discipline — flexible withdrawal mechanisms, detailed transaction histories, and access to account management resources that facilitate the kind of coordinated planning described here. The platform is built for players who think in systems, not transactions.
For the high-roller who has not yet formalized their withdrawal strategy, the starting point is straightforward: engage a qualified tax professional, establish a documented drawdown schedule, and begin treating every cashout decision with the same intentionality you bring to your most significant wagers. The financial difference, compounded over multiple years, is considerable.